How Stacking Cashback Apps and Micro-Wins Builds Real Wealth (Without Spending an Extra Dime)
For decades, mainstream personal finance advice has relied on a model of punitive sacrifice: track every penny, skip your morning coffee, and suffer your way to financial stability.
For most of us, this approach leads to what psychologists call budgetary learned helplessness—a state of mental paralysis where strict restriction triggers cognitive fatigue.
What usually occurs is that we put some money in savings, and then almost instantously, pull out that money to buy something that we “need:. In the end, many consumers to give up on saving altogether.
Meanwhile, major corporations spend billions engineering digital applications to exploit the human brain’s striatum and dopamine pathways, making impulse spending seamless, instantaneous, and chemically addictive.
The solution to this psychological bottleneck is not more willpower or restrictive budgeting. It is an asymmetric counterattack: flipping those exact behavioral mechanics upside down to create an automated Micro-Wins strategy.
Far from being tools designed to separate you from your hard-earned money, modern cashback platforms, card-linking technologies, and automated referral engines allow you to capture corporate marketing dollars and sweep them directly into a High-Yield Savings Account (HYSA) vault to build an emergency fund with zero friction.
1. Beyond Single Apps: The Power of the Cashback Stack
After receiving my first $50.00 from Rakuten, I ignored their constant popus offering me 1% cashback at old Navy. I just tolerated their “cashback is on the way” messages because I was not excited about getting a $5.35 cents check in the mail or would that amount impact my PayPal Account.
Like most consumers I viewed cashback programs as isolated, occasional perks—a $5 rebate on groceries here or a 2% credit card reward there.
However, when you start researching the cashback landscape, you discover there are thousands of cashback applications operating across the digital economy, each competing aggressively for customer acquisition.
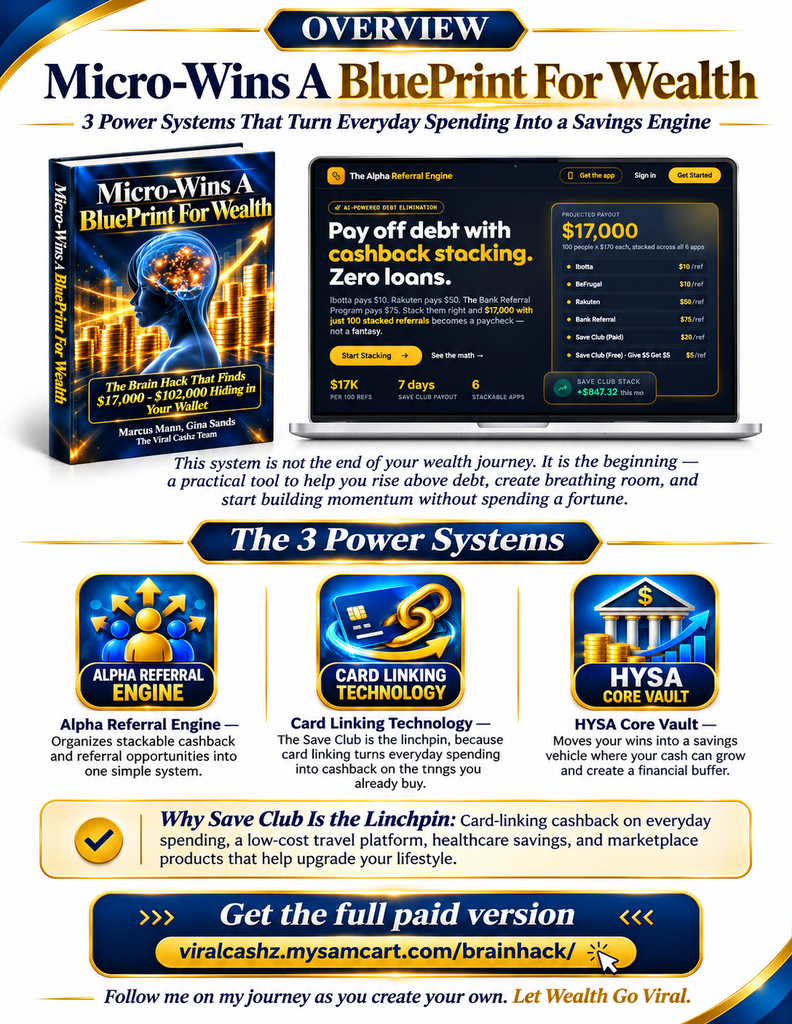
The Alpha Referral Engine was developed to solve this fragmentation by providing a pre-configured architecture that shows users how to stack multiple high-paying apps into a unified cashflow system. Rather than relying on a single app, stacking allows you to layer multiple independent reward streams on top of a single purchase or online action.
Consider shopping portals like TopCashback, a premier platform for everyday shoppers. When you introduce your personal network to a high-utility app like TopCashback, you add another recurring earning layer to your stack.
The power of portal awareness became striking during a recent project: while using Emergent AI to build the technical foundation of the Alpha Referral Engine, it turned out that TopCashback was offering an unexpected $100 cashback bonus for subscribing to that exact Emergent AI software tier.
That single transaction unlocked $100 in liquid capital on an expense already planned for business development.
To ensure you never leave money on the table, tools like Savewise elevate this strategy even further. Savewise tracks and compares rates across 29 different shopping portals daily while simultaneously consolidating credit card-linked merchant offers (such as Amex Offers and Chase Offers). By checking Savewise before checking out, consumers can line up three distinct layers on a single purchase:
- The highest-paying shopping portal rebate.
- An activated card-linked statement credit.
- The underlying credit card rewards rate.
2. The Math of Micro-Wins: Calculating Your Cashflow Potential
To understand the viability of generating real cashflow from cashback apps, we must examine the mathematics of both network referral leverage and passive card-linked sweeping.
The Upfront Referral Stack (10 Referrals)
When you aggregate the core six high-paying cashback programs featured in the Alpha Referral Engine, a single person who registers for all six apps generates $170 in total referral rewards:
| Program | Referral Payout Per Person | Subtotal for 10 Referrals |
|---|---|---|
| Bank Referral | $75.00 | $750.00 |
| Rakuten | $50.00 | $500.00 |
| Save Club (Paid Tier) | $20.00 | $200.00 |
| Ibotta | $10.00 | $100.00 |
| BeFrugal | $10.00 | $100.00 |
| Save Club (Free Tier) | $5.00 | $50.00 |
| Total Stacked Earnings | $170.00 | $1,700.00 |
By introducing just 10 friends or family members to this pre-built cashback stack, you generate $1,700 in immediate, liquid capital. This is not hypothetical income—it represents direct customer acquisition dollars allocated by corporate marketing budgets, captured entirely through your centralized recommendation engine.
The Daily Passive Cashback Sweep
Referrals represent the accelerator, but daily spending forms the unbreakable foundation. When you connect your standard debit or credit cards to automated card-linking networks like The Save Club, everyday spending—groceries, fuel, utility bills, dining, and retail—automatically generates cash back without requiring manual receipt uploads or coupon clipping.
For an average household spending $2,000 per month on qualifying everyday expenses, a modest 3% to 5% card-linked cashback return yields **$60 to $100 per month** ($720 to $1,200 annually). When these micro-rewards are automatically swept into a High-Yield Savings Account earning 4.00%+ APY, the funds compound continuously in the background of your daily life.
3. Network Matching and Real-World Scale
The financial engine becomes even more lucrative when network leverage comes into play. Under The Save Club ecosystem, member activities generate network commissions and cashback matching.
When your 10 referred individuals use their linked cards to save money on their own daily spending, The Save Club matches a portion of their earned cashback and sweeps it into your account as passive residual income. You earn when you spend, and you earn when your network spends.
Real-World Proof: Organic Shopping Cash Back
Skeptics often ask whether cashback apps generate meaningful income without heavy referral recruitment. The proof lies in pure, organic consumer shopping.
Take a real-world case: my daughter, a self-described shopaholic, routinely earns between $500 and $700 per quarter strictly from Rakuten. That payout contains zero referral bonuses. It is derived 100% from organic shopping rebates on purchases she was already making.
When you layer Rakuten, TopCashback, card-linked offers, and Savewise portal optimization together, casual shopping turns into a multi-hundred-dollar quarterly cashflow deposit.
4. Rebuilding Financial Self-Efficacy
Ultimately, the Micro-Wins strategy goes far deeper than extra pocket change. Chronic financial stress destroys self-efficacy—the belief that your personal actions can produce positive financial outcomes. When bills feel overwhelming and budgets feel restrictive, the nervous system stops linking effort to reward.
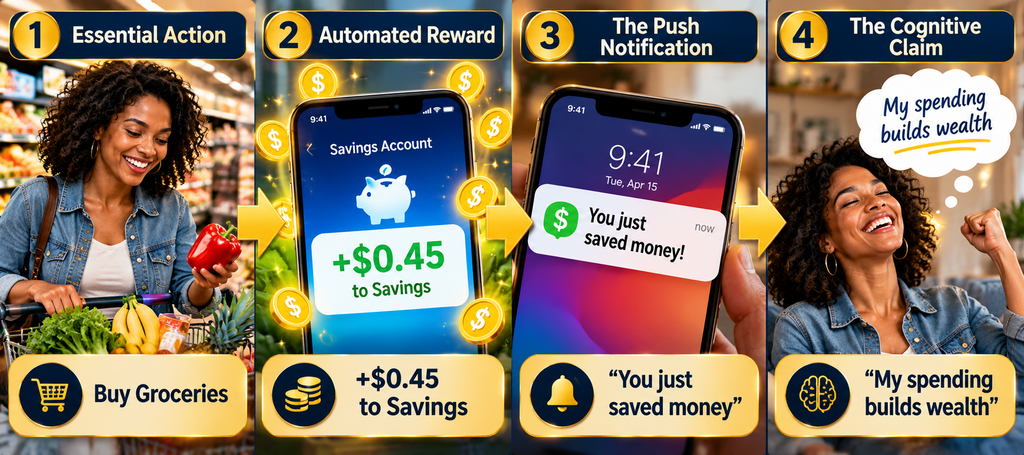
Every time an automated card-link notification pops up showing $5.00 or $10.00 swept into your HYSA vault, your brain’s striatum receives tangible evidence that your choices matter.
By systematically redirecting corporate marketing dollars into your private emergency fund, you build real financial resilience, eliminate debt without taking on new loans, and create a sustainable cashflow engine built for the modern digital economy.