How To Borrow $500 Instantly And Pay it Off Quickly
Safe, Low-Cost Ways To Bridge the Gap with CashBack Referrals
Borrow $500 with no credit check and Pay It Back Using CashBack Rewards
I Need $500 to Pay My Rent
There have been times in my life when funds were tight between paychecks, and I didn’t have anywhere to turn for a loan. When this happens and life seem limited. You might be tempted to do a payday loan.
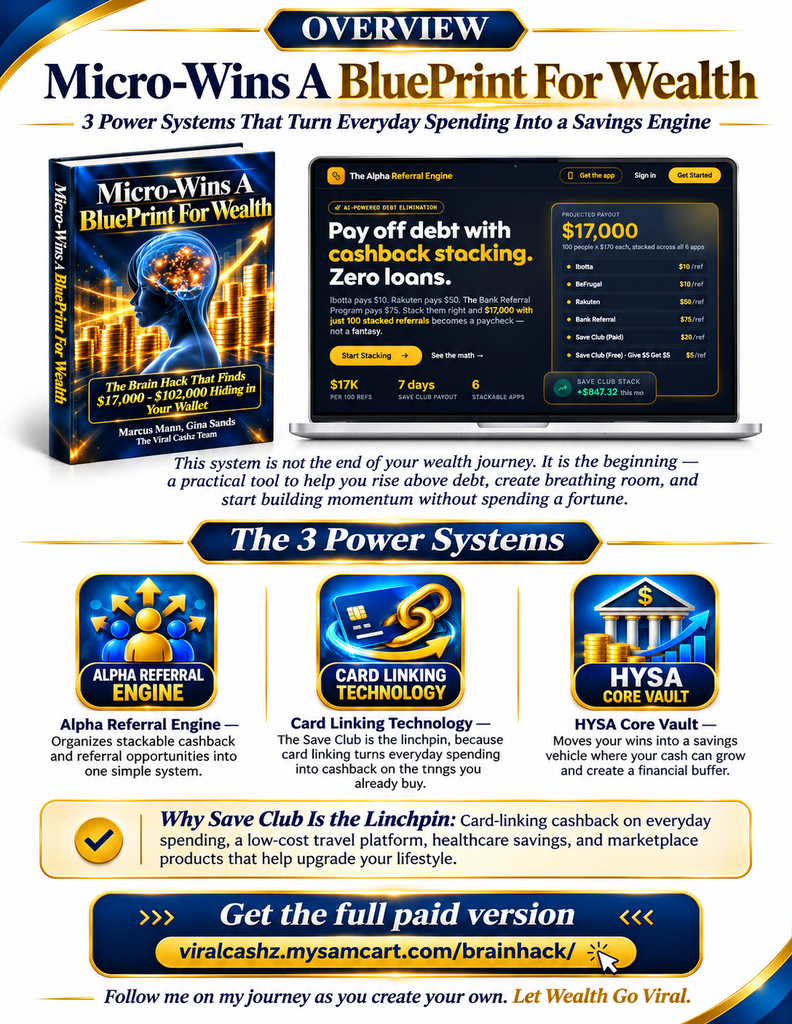
While these services offer a temporary solution, My ebook, Micro-Win A BluePrint for Wealth provides a possible solution for you to pay back those loans using cashback referral bonuses that pay you real cash for referring your friends and neighbors to the app.
Although you may need to temporarily turn to payday advance apps, the ebook shows you a better way to meet your emergency needs. And while you need the loans temporarily, only use those payday apps that offer a referral bonuses for referring your friends.
Unfortunately, the payday advance apps are predatory, and to be honest, FACEBOOK temporarily would nt allow me to post information regarding my ebook, because it stated, that title of my ebook seem like it was trying to get money from my followers?
Another online platform declared that it would not allow me to post because the possible income that I showed was misleading. While it may be true, that earning $12,000 in 10 days seems like an unobtainable obstacle, my thoughts are always, anything is possible.
And, when you consider that if someone is really struggling with their finances and can see a blueprint that by referring 100, to 1,000 struggling individuals to a program that can benefit them both in the long term: And with access to billions of people online, it is not only possible but it is doable.
Facebook has 3.07 billion monthly active users worldwide, making it the most-used social media platform globally. [1, 2]
The focus of the ebook is to make indiviuals aware of the power of cashback referral rewards to change their cashflow and provide temporary to long-term income so they can breathe.
From my vantage point, the concept that I share in the eBook is a significantly better options than drowing in payday loan hell.
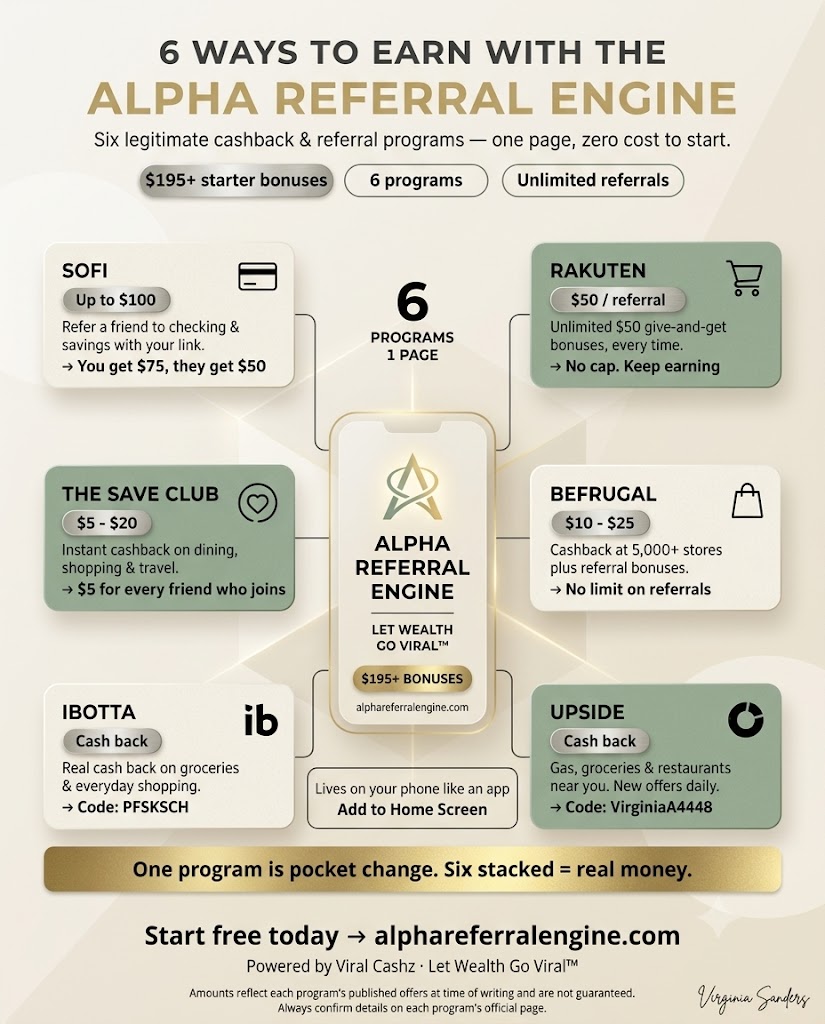
Many of the programs in the ebook that are loaded onto the Alphareferral Engine are free the difference is that you focus the spending you were already going to do toward those programs that will pay you for buying bread and mlk, filling your car with gas or buying a gift.
Then the power of cashback referrals kicks in. When you refer your friends and neighbors those giant conglomerates send you cash for doing what you have been doing for free.
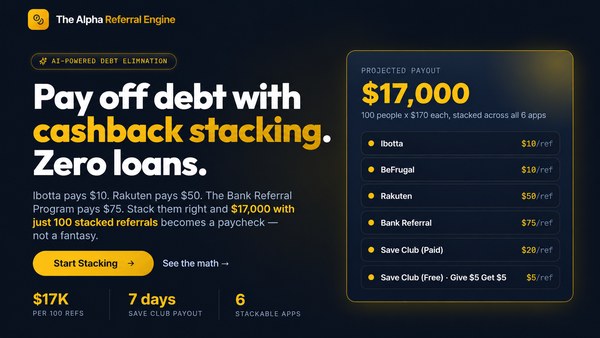
Programs like Rakuten will send you $50.00 when you go to Walmart and purchase $50.00 worth of goods. When you tell your friend about it and they do the same, Rakuten send you $50.00 and your friend. The Kicker with Rakuten is that is NO LIMIT to the number of friends you can refer.
You have to plan for Rakuten because they pay quarterly: But if you are facing a rent increase at the beginning of the year, you have time to get your ducks in a row and if you have friends or family that are not already enrolled in Rakuten, sign them up and your $500,, your $5,000 (with 100 referrals) will be in your Paypal Account or Your checking Account when the increase hits.
Ibotta and Be Frugal, will pay you $10.00 per referral.
The Bank Referral Program pays from $50 to $75.00 per referral when you refer your friends. The bank pays out in 7-10 days after you open a checking/savings account and deposit $50.00. How many friends can you refer to that app. They also pay a $35.00 bonus when you open the account. with 10 friends, you have earned $750.00.
The Save Club Free Program allows you to download their free app and when your friends and family use the app, go out to dinner, spend $25.00 they pay you $5.00 and your friend get $5.00 added to their accont.
The Save Club paid program will cost you $79.97 (60.00 sign up fee then $19.97 per month) However as soon as you join and refer your friends, they will pay you $20.00 per referral and they pay every week. 10 friends = $200.00 but you have access to a multitude of benefits: travel at a disco9unt, Lower my bills, they negotiate your expenses with the carriers. You also start building a network that when your friends join and they tell their friends, you monthly check increases.
Borrow the Money You Need But Get The Micro-Wins BluePrint – Never Borrow Again
Borrowing money using reputable apps can be a safe, cost-effective way to pay the bills, but you shouldn’t overuse them, and it’s important to choose wisely. Here are the best cash advance apps for borrowing at least $100.
When you’re strapped for cash and need to borrow $500 quickly, you may be tempted to consider getting a payday loan to help get by until your next paycheck arrives.
Always Choose those app that pay for referrals… since our core way to earn money is by using referral markeing.
However, there are better options that won’t cost you exorbitantly high interest rates, potentially worsening your financial situation.
One of the best ways to borrow $500 fast is with CASHAPP.
These services, which essentially let you borrow from your future paycheck, can be faster, safer, and far more affordable than high-risk alternatives such as payday loans.
Let’s look at some of the most affordable choices for $500 cash advances that you can access instantly, plus other ways to borrow.
Can you get a $500 cash advance with no credit check?
If you’re strapped for cash to the tune of $500 but worried you might have limited options for financing due to poor credit, you should know that there are still ways to get the money you need without resorting to higher-risk, higher-cost options (such as payday loans or “buy now, pay later”). In fact, there are ways to borrow money with and without a credit check.
Several paycheck advance apps provide $500 paycheck advances with no credit check required, which is one of the top options we recommend for instant funding from time to time. Other safe alternatives include several types of loans and lines of credit, which also allow you to borrow more if you need to. Because they have minimal requirements and there are so many reputable options, we’ll focus on paycheck advance apps we recommend.
Cash advances vs. paycheck advances
Apps that provide paycheck advances, sometimes referred to as “cash advance apps,” do not offer traditional cash advances. A cash advance is a different type of service offered by credit cards, in which you withdraw cash against your credit line, often with fees and high interest rates that kick in immediately. Even though you might sometimes see paycheck advance apps called cash advance apps, these don’t provide true cash advances.
Apps we recommend for $500 advances
Cash Advance
Cash App is the one I would recommend They provide you options for repayment
Best for Flexible repayment options
Cash App Borrow provides more repayment flexibility than some paycheck advances that set automatic due dates. If you borrow money, Cash App lets you set up a repayment plan that fits your needs and budget.
With Cash App Borrow, the money lands in your bank account instantly. Rather than an interest rate, there is a flat fee for the service calculated as a percentage of the amount you borrow.
To be eligible for Cash App Borrow, you must have direct deposits of $300 or more into your Cash App account each month or link your Cash App account with an external account that receives $500 or more in monthly deposits.
You can also take out multiple loans, as long as you don’t have a past-due balance on other Cash App Borrow loans.
Cash Advance
Tilt – Get $30.00 For Every Friend that signs up using your link and takes a cash advance within 30 days
Up to $500 right now
For the moments that can’t wait, get $10–$500 instantly.‡
No interest, late fees, or credit check.
Instant delivery is optional. Fees may apply.
Best for Great mobile app
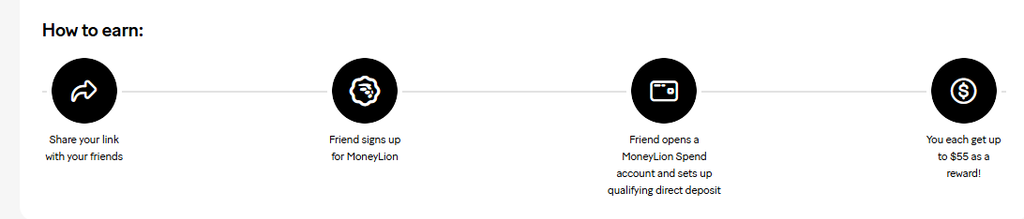
MoneyLion Use my Code $GladCan706
Best for paycheck advances over $500
Living paycheck to paycheck is a struggle. MoneyLion offers significant potential paycheck advances to help you pay your bills while you wait for your next payday. With MoneyLions Cash Out feature, you can borrow up to $150 per day or a maximum of
On average, EarnIn users can access about $85 per day, but you may be eligible for more or less. EarnIn also offers strong overdraft protection, called Balance Shield, that automatically transfers $100 per day (up to $1,000 per month) from your future earnings into your bank account when your balance falls below a certain threshold.
Current
Best for People with consistent incomes
With Current‘s10 Paycheck Advance, you can get an advance of up to $750 without a credit check or interest.1 You don’t need a Current Spend Account to borrow money, but you do need consistent recurring payroll deposits of at least $200 in an external account or a Current account.
So, freelancers with inconsistent paychecks are unlikely to qualify. Current determines how much you’re eligible to borrow using a number of factors, including your payroll deposit history, spending habits, and transaction history. This is standard fare for many paycheck advance apps.
Paycheck advances are typically transferred within three business days, but you can pay a fee that varies by the amount of your advance if you need funds instantly.2 There is no limit on the number of advances you take. You can repay an advance early, or it can be automatically deducted from your next paycheck.
Other ways to borrow $500 quickly
Small-dollar loans from banks
Some banks offer small-dollar loans that can help you borrow $500 when you’re short on cash. These loans usually have relatively low interest rates and fees, and they’re available in amounts of up to $2,500. However, if you have poor credit or a limited banking history, you may have difficulty getting approved for a bank loan.
It’s also worth noting that banks may charge application fees or require you to be a customer. And the process of applying and getting approved can take a while, which may be an issue if you need funds for an emergency expense. When you borrow money from a bank, you should be extra diligent about making your loan payments on time. Banks report payment activity to credit bureaus, and late payments could hurt your credit score and ability to borrow in the future.
Payday alternative loans (PALs) from credit unions
Payday alternative loans from credit unions can be a safe, affordable way to borrow $500, especially when compared to payday loans. Credit unions usually offer competitively low interest rates and fewer fees than traditional banks, making it easier to pay off a loan without falling into debt.
PALs are available in amounts up to $2,000 with APRs up to 28% and terms between one and six months. PALs are specifically designed for borrowers with bad credit, and many credit unions also offer credit coaching.
Still, approval isn’t guaranteed. Plus, you often have to be a credit union member with active accounts to access payday alternative loans, and some credit unions have eligibility rules.
Personal loans
Many banks, credit unions, and fintech companies offer personal loans, with borrowing minimums as low as $500 or $1,000. Some lenders, however, require you to borrow much more.
For example, SoFi’s minimum is $5,000. A handful of companies let you borrow as little as $500, such as Members 1st Federal Credit Union and Credit Human. These loans have fixed interest rates and repayment terms that tend to range from two to seven years, so you could have much longer to pay the money back than with a cash advance app or PAL.
Personal loans often require a credit check for approval, and your credit helps to determine your rate. The average APR for a personal loan is around 11% to 12%, but you generally pay more if you have bad credit. You may have to pay loan origination fees, late payment fees, and sometimes prepayment fees for personal loans.
Personal lines of credit
A personal line of credit lets you borrow up to a set limit and withdraw what you need, when you need it. You pay interest only on the amount you borrow.
Some lenders, like Regions Bank, Credit Human, and Golden1 Credit Union, offer lines of credit as low as $500. The drawbacks of lines of credit are similar to those of personal loans. They can have significant interest rates and may also have fees, but they could be a better alternative than a fixed-rate, lump-sum personal loan if you’re not sure how much you need to borrow.
Why you shouldn’t take out a payday loan to borrow money
Traditional payday loans are something you should try to avoid at all costs. While they may seem like a quick fix to helping you pay your bills, they often come with sky-high interest rates and limited repayment windows.
Some payday loans may charge fees equivalent to APRs of 400% or more, which is astronomical compared to loan and credit card rates.
If you can’t repay a payday loan by your next paycheck, the lender may roll the balance into a new loan, which can mean additional fees. It could also put you on a hamster wheel of debt that may be impossible to get off.
FAQs
How can I get $500 fast?
One of the fastest ways to get $500 is with a paycheck advance app. There are several fintech companies, like Chime, EarnIn, and Dave, that offer paycheck advances with no interest, limited fees, and no credit checks.
You should avoid the payday loans that charge extremely high interest rates and fees at all costs.
Can I borrow $500 with bad credit?
Yes, it is possible to borrow $500 even with bad credit. Apps like Chime, Dave, and EarnIn don’t require a credit check for paycheck advances. This is beneficial if you have bad credit, as it helps you avoid hard inquiries that could cause further damage or jeopardize your ability to borrow money.
Bottom line
When you need $500 fast, whether it’s for an emergency, to buy something you really need, or just to cover your grocery bill until payday, paycheck advance apps can be the safest, most affordable option available.
Several fintech companies, like MoneyLion, Cash App, and Tilt offer cash or paycheck advances to help you bridge the gap without high interest, long approval timelines, or credit checks.
Often, you can borrow $500 instantly for a small fee.
Small-dollar bank loans, credit union PALs, personal loans, and lines of credit can also be good options to borrow money, but they can have higher fees and longer approval times. The key is to choose an option with the lowest costs, fees you can comfortably manage, and repayment terms you can afford, so you can cover your expenses now without creating long-term financial stress.
What pushed me to create The Micro-Wins BluePrint were the suggestions from sites like Finance Buzz,
Find ways to increase your income
Perhaps the best alternative to a relatively small cash advance is temporarily increasing your income. This might come through reselling items in your home or at thrift stores, gig work through an app like Uber Eats or Instacart, or offering a service like babysitting or pet-sitting.
My way was to create the Micro-Win BluePrint to give you an easier path out of the deathtrap of loans of any kind and find a way to create money that you can use to pay off debts and start your path toward Financial Freedom