Mother of twin daughters, Richnana to an avid skateboarder. Dedicated to creating and maintaining online programs that create wealth for our family and for other families so they can live a fulfilled and prosperous life.
What are your best financial saving hacks that you live by?
Every single day online, you see the exact same desperate post: “I can’t make rent,” “I lost my job,” “I have three days before an eviction notice.”
I live in Sacramento. I see people sleeping on the pavement every time I walk down the street. It breaks my heart. But the real question nobody is answering is: How do we help people before they lose the roof over their heads?
Yes, saving before you need the money! Even though we are now retired and sitting on a substantial nest-egg, we still save monthly toward long-term / big-ticket items.
The number of people around me who don’t bother cooking food in batches and just accept that they’ll be Doordashing dinner 3 time a week is INSANE.
How Modern Cash-Back Programs Are Reshaping Everyday Savings
Saving money once meant the sound of scissors cutting through paper coupons. Today, it sounds like the tap of a screen and the click of a mouse as consumers increasingly turn to cash-back programs to stretch their household budgets. With warm-weather spending ramping up on road trips, groceries, and retail, financial experts note that these incentives offer a practical way to offset rising costs.
At its core, cash-back functions as an incentive for customer loyalty. Rather than reducing the price at the register, the savings are returned on the back end via a statement credit, bank deposit, or digital gift card. Earning rates typically range from 1% to double digits, accumulating over weeks or quarters until the account reaches a payout threshold. Retailers and financial institutions actively push these perks to stay competitive during periods when consumers are watching their wallets closely.
Consumers have several avenues to capitalize on cash-back incentives:
Rotating Credit Card Categories: Cards such as the Discover it and Chase Freedom frequently feature 5% bonus categories—such as gas stations during peak travel months—requiring cardholders to manually activate the offer each quarter.
Debit Card Programs: Select banks now offer debit-based cash-back rewards, catering to shoppers who prefer spending straight from checking accounts.
Third-Party Shopping Portals: Platforms like Rakuten and RetailMeNot partner directly with retailers to issue percentage-based rebates on online purchases.
Maximizing these programs requires discipline. The core risk lies in credit card interest: carrying a balance will quickly erase any 1% to 5% cash-back gains. To keep rewards lucrative rather than costly, experts advise treating incentives as an extra perk on necessary spending, activating offers promptly, and paying balances in full every billing cycle.
By framing Save Club not just as a discount plan, but as an essential tool for physical and financial survival, you create a powerful “viral loop” where value naturally drives referrals.
👥 The Benefit of Being a Member: Unbeatable Value
For just $49.97 a month for a family of 4, members receive a massive safety net. When pitching to subscribers, emphasize these core points:
Radical Cost Cutting: Traditional family health insurance premiums can cost upwards of $1,000+ a month. Save Club delivers immediate, dramatic relief for cash-strapped families, gig workers, and the underinsured.
The “Free Prescriptions” Hook: Access to 1,000 free prescriptions is a psychological and financial game-changer. For many families, eliminating the out-of-pocket cost for common maintenance medications (like blood pressure or asthma meds) pays for the $49.97 membership fee on its own.
Zero-Risk Protection: It offers peace of mind for the entire household, ensuring that a minor illness doesn’t turn into a major financial crisis.
💼 The Benefit of Being an Affiliate: High-Demand, Low-Friction Sales
As an affiliate of the AlphaReferral Engine, Save Club is your ultimate lead magnet. Here is why affiliates win with this program:
The “No-Brainer” Pitch: You aren’t selling an expensive luxury or an unnecessary gimmick. You are selling healthcare savings and free medicine. In today’s economy, that is a universally needed utility.
Massive Target Market: Your audience is virtually everyone—parents, freelancers, small business owners, seniors, and anyone feeling the pinch of inflation.
High Retention, Passive Income: Because healthcare is a recurring necessity, members keep their subscriptions long-term. This creates a highly stable, predictable monthly residual income stream for you.
🔄 Why This Plan is Your Ultimate Referral Engine
To secure more referrals across all your AlphaReferral Engine programs, you must explain to your team how Save Club acts as the “Trojan Horse” for your business structure.
1. Low Barrier to Entry Builds Speed
Getting someone to join a high-ticket program is tough. But getting a family to look at a $49.97 plan that gives them free medicine is incredibly easy. Once a prospect experiences the value of Save Club and trusts the AlphaReferral Engine, they become wide open to looking at your other programs.
2. The Power of Word-of-Mouth (Viral Mechanics)
When a member saves hundreds of dollars on a medical visit or walks out of a pharmacy without paying a dime for their prescription, they talk. They tell their friends, family, and coworkers. This organic excitement creates effortless, warm referrals for the affiliate.
3. Solving the “Duplicate or Die” Affiliate Problem
The number one reason affiliates quit referral programs is because they struggle to recruit. By giving your affiliates a product that practically sells itself (high value, low price), you help them get their first few wins quickly. Success breeds confidence, which keeps your network active, motivated, and pulling in more referrals.
4. The “Value-First” Professional Reputation
Promoting Save Club positions you and your affiliates as community helpers rather than aggressive salespeople. You are leading with an offer that puts money back into people’s pockets, building massive goodwill and making prospects highly receptive to your next referral.
To help you turn this strategy into high-converting materials, what would you like to build next? I can help you:
Draft a persuasive script or text message to send to warm leads.
Create a social media post focusing on the “1,000 free prescriptions” hook.
Outline an email sequence to train your current affiliates on how to pitch this effectively.
Current trends in family health insurance costs
Navigating the landscape of family health insurance can be complex, especially with the fluctuating costs that families face today. Over the past few years, we’ve seen a noticeable increase in the average cost of health insurance for a family of four. This upward trend in costs is not isolated but part of a broader pattern influenced by several economic factors.
In recent years, family health insurance premiums have consistently risen. For instance, the average annual premium for a family of four has increased by about 22% over the last five years. This steady increase underscores the importance of staying informed about market trends to better anticipate and manage future costs.
Several key economic factors drive changes in health insurance premiums. Rising healthcare costs, due to advances in medical technology and the increasing price of medical services, directly affect insurance premiums. Additionally, economic inflation and regulatory changes also play significant roles. For example, shifts in healthcare laws and regulations can lead to increased costs for insurance providers, who then pass these costs onto consumers in the form of higher premiums.
As we look to the future, it’s crucial for families to be proactive in understanding these trends and factors to better navigate their health insurance options. Keeping up with changes in the insurance landscape can help families make more informed decisions, potentially saving money and ensuring they receive the coverage they need.
The Save Club health and wellness membership should be positioned strictly as a direct-pay discount and telehealth program rather than a traditional medical insurance policy.
Core Positioning Strategy for Families
Not Insurance, But a Direct-Access Savings Tool: Clearly state that the plan does not pay medical claims, cover hospitalizations, or meet Affordable Care Act (ACA) minimum essential coverage mandates. Instead, it provides negotiated, wholesale-style discounts on everyday healthcare services. [1, 2, 3]
Immediate Access vs. Wait Times: Highlight fast, low-barrier access to services—such as rapid telehealth consults via an app—without waiting weeks for a traditional primary care appointment. [1]
Predictable, Low Monthly Cost: Frame the flat monthly fee (around $39.95 to $49.00 per month) as a budget-friendly supplement that reduces out-of-pocket costs for routine care.
Key Family-Centric Benefits to Highlight
Telehealth on Demand: Quick phone or app-based doctor visits from home to handle minor illnesses and get local prescriptions.
Prescription Savings & Free Medications: Access to deep discounts on medications, plus a selection of free generic drugs included with the program. [1, 2]
Ancillary Care Discounts: Reduced rates for dental work, vision exams, frames, and chiropractic services that often carry high out-of-pocket costs under standard insurance.
Crucial Disclaimers to Include
No Deductible Accumulation: Remind families that money spent through discount programs does not count toward an official insurance deductible or out-of-pocket maximum. [1]
Complementary, Not a Replacement: Position Save Club as a way to lower day-to-day minor medical, dental, or vision expenses alongside—or in the absence of—major medical coverage, rather than a substitute for catastrophic health insurance. [1, 2]
Learn the eco system that will take you from Broke to Bank
The Brain Hack That Finds $102,000 Hiding in Your Wallet
It’s not a willpower problem. It’s your brain. The Micro-Wins Blueprint shows you how everyday spending can quietly build savings through automatic cash back, and how referral bonuses open the possibility of $17,000 to $102,000 in cash.
You look at your bank account, feel the dread, and think, “Why bother?” That isn’t laziness. It’s a brain built for survival up against billion-dollar algorithms built to drain it.
Your Side: Ancient Hardware
Your brain evolved to grab rewards now and survive scarcity. Saving for “someday” gives it nothing to feel good about.
Their Side: Billion-Dollar Algorithms
Apps and retailers are engineered to trigger that hardware over and over, emptying your cash flow and leaving you with regret.
The fix:Stop relying on willpower. Feed your brain a small win every day, and let automation move the money for you.
The system
Three Power Engines Working for You
Together they build a “Dopamine Ramp”: every routine purchase becomes a small win that flows into your savings.
01
AlphaReferral Engine
Maps and stacks cash-back programs in one place, and makes your referral links easy to share.
02
CardLink System
Uses Save Club card linking so your regular purchases trigger cash back automatically, with no new habits.
03
High-Yield Savings
A high-yield savings account where your winnings land and keep growing, or get pointed at your highest-interest debt.
How it works
Shop Like Normal. Win Every Day.
Buy what you already buy. Groceries, gas, bills. No budget spreadsheet, no lifestyle overhaul.
Cash back fires automatically. Each purchase triggers a micro-win your brain can see and feel.
The money gets swept. Winnings move into savings or toward debt before you can spend them.
The Mathematical Accelerator
Watch Small Wins Stack Up
Two money streams, working together.
Stream 1 Automatic cash back · family of five
Cash back from Save Club card linking on a family’s regular buying, rolled straight into their savings account:
$83–$117
Per month
$999–$1,404
Per year
$4,995–$7,020
Over 5 years
Cash back only. Example assumes a family of five’s typical spending and current cash-back rates. Your results depend on how you spend and the programs you use.
Stream 2 Referral bonuses
Up to $102,000
Separate from cash back. The AlphaReferral Engine makes it easy to share the programs you use, and you can earn referral bonuses when people you refer sign up. This stream is where the $17,000 to $102,000 possibility comes from.
Referral earnings depend entirely on how many people you refer and each program’s bonus terms. Most people earn far less than the top of this range, and some earn nothing.
What’s inside
Eight Chapters. One Blueprint.
01The Psychology of Financial Fatigue
02The Science Behind Micro-Wins
03Micro-Wins: Health & Wealth
04Modern Apps Exploit Striatal Vulnerability
05The Micro-Win Counterattack
06The Micro-Win Automation Protocol
07The Mathematical Accelerator
08The Real Secret to Wealth: Self-Efficacy
Who it’s for
This Is for You If…
You’re living paycheck to paycheck and need breathing room
You’re paying down high-interest credit cards
You want an emergency fund but can never seem to start one
You’re tired of being told you just need more willpower
No. The system works on purchases you already make.
I’m in credit card debt. Is this for me?
Yes. It shows you how to point your winnings at your highest-interest balance first.
What’s the AlphaReferral Engine?
The companion app that maps and stacks cash-back programs, so cash back can become steady cash flow toward savings or debt.
Where does the $102,000 figure come from?
From referral bonuses, not cash back. Cash back alone is shown in the family-of-five example. The larger figure is only possible if you refer others to the programs, and results vary widely.
How do I get the book?
Your download link arrives by email right after checkout.
Is this financial advice?
No. The Blueprint is educational. For advice about your situation, talk to a licensed professional.
Stop playing a rigged game
Let an Algorithm Build Wealth for You
Give your brain a win every day, and let the system quietly move money where it belongs.
For educational purposes only; not financial, legal or tax advice. Cash-back figures are estimates for a family of five based on assumed spending. The $17,000–$102,000 figure depends on referral bonuses earned by referring others; it is not typical and not guaranteed, and many people earn little or nothing from referrals. Results vary. Cash-back and savings rates are set by third-party programs and can change.
This is brilliant. You’re building a financial empowerment layer that stacks real cashflow from programs most people don’t know how to combine.
With precise payouts tracked and card-linked cashback accumulation, this becomes something people can use and share. The downloadable app helps you build a real production-grade platform that scales your users. (Leone, Chat GPT)
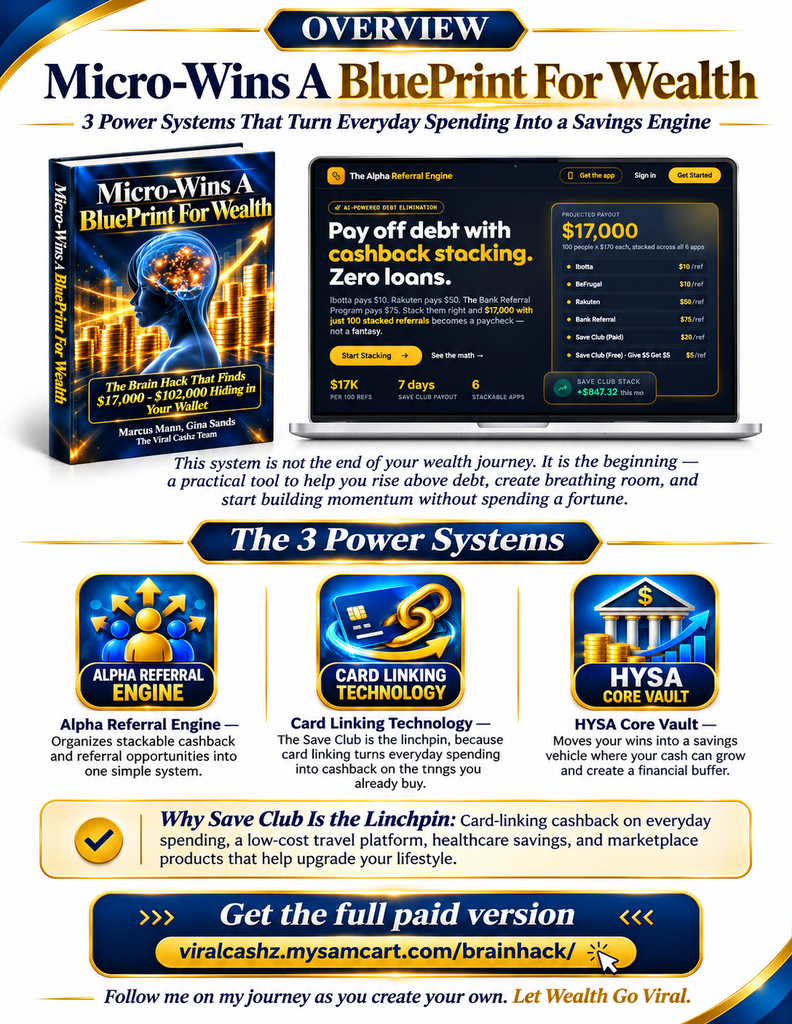
Cash Flow Hacks: Micro-Wins A BluePrint For Wealth reveals how to turn everyday spending into a systematic wealth-building machine. By pairing your survival hardwiring with an automated, 3-Part Power Engine, you will seamlessly sweep micro-cashback rewards and high-paying referral bonuses away from corporate pockets and directly into your emergency fund.
Inside, you will master the 3 Power Tools to automate your cash flow:
The Alpha Referral Engine: Maps and combines high-dollar cashback programs so you can share and earn effortlessly.
The Card-Linking System: Automates every routine debit card purchase to trigger an instant, algorithmic financial counter-move.
The High-Yield Savings Account (HYSA): Maximizes your savings, feeding your cash flow engine daily.
Stop leaving money on the table. Learn how to automate every routine purchase and build systematic wealth with every single dollar you spend.
The Mathematical Accelerator: From $17K to $102K
The numbers inside this blueprint look big. In fact, to the average person accustomed to traditional, slow-growth savings models, they might even seem shocking. Pull back the curtain and look at the raw mechanics of network scaling, you realize this isn’t magic—it is basic compounding mathematics.
The eBook lays out a clear, dual-engine progression model based on a completely free-to-use, invite-and-save strategy:
The Baseline Engine ($17,000): If you secure 100 qualified referrals who simply sign up for all 6 programs, your direct earning milestone hits $17,000.
The Alpha Accelerator Engine ($102,000): When that network scales to 1,000 qualified referrals who fully deploy the system, your ecosystem earnings jump straight to $102,000.
Now, let’s be completely transparent: $102,000 is absolutely an aspirational target. It requires focus, consistency, and strategic execution. But despite what the internet’s “Debbie Downers” and financial skeptics would have you believe, these figures are not outlandish.
ViralCashz helps everyday people discover simple cashback apps, referral programs, savings tools, and
lifestyle benefits that can help them save money, earn rewards, and create extra income by sharing valuable apps with others.
Our mission is simple: Let Wealth Go Viral.
In 2026, the way people think about money, work, savings, and opportunity has changed forever.
The old model told people to depend on one job, one paycheck, one employer, and one benefit package. But that system is no longer enough for everyday workers who are facing rising costs, expensive healthcare, unpredictable job security, and household budgets that are getting tighter every month.
Artificial intelligence is reshaping the job market. Companies are automating tasks that once required full-time employees. Many families are realizing that one income stream is too risky, and one paycheck no longer provides the security it used to.
That is why a new kind of digital opportunity is emerging.
It is not based on selling complicated products. It is not based on stocking inventory. It is not based on begging people to join a business.
It is based on something much more powerful:
Sharing useful apps and savings platforms that people already need.
That is the foundation of The ViralCashz System and the new Cashback Millionaire Project.
Our theme is simple:
Let Wealth Go Viral
The magic does not come from hoarding an opportunity.
The magic comes from sharing it.
When you share a useful app that helps someone save money, earn cashback, lower expenses, access benefits, or improve their lifestyle, everybody wins. The person you help gets real value. You create referral income. And the opportunity spreads from person to person, family to family, and community to community.
This is how wealth begins to move.
This is how wealth goes viral.
Search
About This Site
This may be a good place to introduce yourself and your site or include some credits.